Expats can buy portfolio bonds through international insurers and investment providers that accept clients in their country of residence.
Unlike buying an individual bond through a brokerage account, this involves opening an insurance-based investment policy that can hold funds, equities, fixed-income assets and other permitted investments.
Before investing, expats should check whether the provider can continue serving them if they move countries, how the policy will be taxed where they live, and whether its fees and withdrawal terms justify using the additional investment wrapper.
Key Takeaways
- Portfolio bonds are investment wrappers, not bonds themselves.
- Portfolio bonds hold diverse assets through an insurance-based structure.
- Tax residency can be more important than nationality when determining how an expat’s portfolio bond is treated.
- A portfolio bond can become less suitable after relocation or major changes in financial circumstances.
My contact details are hello@adamfayed.com and WhatsApp +44-7393-450-837 if you have any questions.
The information in this article is for general guidance only. It does not constitute financial, legal, or tax advice, and is not a recommendation or solicitation to invest. Some facts may have changed since the time of writing.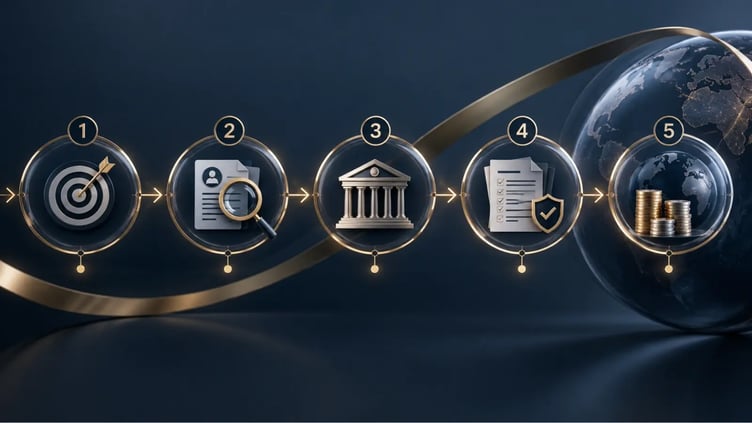
What are portfolio bonds?
Portfolio bonds are insurance-based investment products that allow investors to hold a range of underlying assets, such as bonds, equities, and investment funds, within a single policy structure.
For expats, the term commonly refers to international investment bonds, also called offshore portfolio bonds.
These are typically life assurance contracts issued by insurance companies in jurisdictions such as Luxembourg, Ireland, and the Isle of Man.
Despite their name, portfolio bonds are not individual fixed-income securities like government or corporate bonds.
Instead, they function as investment wrappers that hold a selection of permitted assets.
How do portfolio bonds work?
A portfolio bond works by placing an investor's capital inside an insurance policy, which then holds and manages selected underlying investments according to the product's terms.
The process generally follows these steps:
1. The investor contributes capital.
The policyholder deposits a lump sum or makes contributions, subject to the provider's minimum investment requirements.
2. The insurance provider issues the policy.
The investment is held within a life assurance structure.
3. Capital is allocated to underlying investments.
Depending on the product, the investor may select funds, fixed-income assets, equities, and other permitted investments.
4. The portfolio's value changes over time.
Returns depend on market performance, investment income, fees, and other applicable costs.
5. The investor withdraws or restructures the investment.
Partial withdrawals, fund switches, and policy surrender are governed by the contract and relevant tax rules.
For expats, the structure may offer investment flexibility and potential tax planning features in certain jurisdictions.
However, these benefits are not universal, and a policy's suitability can change when the investor relocates.
How to purchase a portfolio bond for expats?
Expats can purchase a portfolio bond by defining their investment goals, confirming eligibility, selecting a regulated provider, completing compliance checks, and funding a policy aligned with their financial needs.
The process typically involves the following steps.
1. Define your investment objectives
Start by identifying your investment goals, time horizon, income needs, and tolerance for losses.
Common objectives include:
- Building long-term wealth
- Generating investment income
- Diversifying across currencies and markets
- Preserving capital for retirement
- Funding a future relocation or property purchase
For example, an expat saving for a property within three years may need a more liquid and conservative allocation than someone investing for retirement over two decades.
2. Confirm eligibility based on your country of residence
Check whether your current country of residence, tax residency, and financial circumstances make you eligible for the portfolio bond.
Eligibility may depend on:
- Country of residence and tax residency
- Citizenship
- Minimum investment amount
- Source of funds and source of wealth
- Applicable regulatory restrictions
A US citizen living in Singapore, a British expat in the UAE, and a Filipino professional in Hong Kong may face different onboarding requirements.
Tax residency and country of residence often affect eligibility and tax treatment more directly than nationality alone.
3. Choose a regulated provider or qualified adviser
Select a regulated insurer or qualified financial adviser that serves clients in your jurisdiction and offers a suitable portfolio bond structure.
When comparing providers, verify:
|
Factor |
What to check |
|
Regulatory status |
Is the insurer or adviser authorized in its jurisdiction? |
|
Financial strength |
Is the insurer financially stable and able to meet its obligations? |
|
Investment access |
Which funds and asset classes can the policy hold? |
|
Minimum investment |
How much capital is required? |
|
Total fees |
What policy, fund, adviser, platform, and withdrawal charges apply? |
|
Geographic eligibility |
Does the provider accept residents of your current and potential future countries? |
|
Exit provisions |
Can you withdraw, surrender, or transfer the policy at a reasonable cost? |
An offshore location does not automatically mean a provider is more secure or tax-efficient.
Confirm the issuing entity and the protections available in its jurisdiction.
4. Review the underlying investment options
Review the assets available within the portfolio bond because they determine much of its risk, return potential, and market exposure.
Depending on the provider, options may include:
- Government bond funds
- Corporate bond funds
- Global equity funds
- Multi-asset portfolios
- Money market funds
- Alternative investments
A portfolio bond is an insurance-based investment wrapper, not a bond itself.
Investors seeking income should assess the underlying assets, credit quality, maturity profile, volatility, and interest-rate exposure.
5. Compare the total costs
Compare all applicable charges before investing because layered fees can reduce net returns over time.
Potential costs include:
- Establishment or allocation charges
- Annual policy and administration fees
- Fund management expenses
- Adviser or platform fees
- Transaction and switching costs
- Withdrawal or surrender charges
Request a complete fee schedule and illustration showing projected values after applicable charges.
6. Complete compliance and onboarding requirements
Prepare the identity, tax residency, and financial documentation required to open the portfolio bond.
Common requirements include:
- Passport or government-issued identification
- Proof of residential address
- Tax identification numbers
- Evidence of tax residency
- Source-of-funds documentation
- Source-of-wealth information
- Completed application and risk assessment forms
Additional checks may apply to applicants with multiple tax residencies, complex ownership structures, or politically exposed person status.
7. Fund and activate the policy
After approval, sign the policy documents, transfer the investment capital, and confirm the selected investment allocation.
Before funding the policy, verify:
- Investment and transfer currencies
- Applicable bank and transfer fees
- Investment dealing timelines
- Minimum contribution requirements
- Whether the allocation can be changed later
- Availability of currency-hedged options
Choose an allocation that reflects your objectives, liquidity needs, and ability to withstand losses rather than focusing only on projected returns.
8. Review the policy after relocating
Review your portfolio bond whenever your country of residence or tax residency changes because relocation may affect its tax treatment and administration.
Notify the provider when your:
- Country of residence changes
- Tax residency changes
- Citizenship or reporting status changes
- Investment objectives materially change
Confirm whether the policy can remain active, whether additional contributions or withdrawals are permitted, and whether new tax or reporting obligations apply.
A portfolio bond should form part of an ongoing cross-border financial plan rather than be treated as a one-time purchase.
What to consider when buying portfolio bonds as an expat?
Expats should understand how a portfolio bond’s tax treatment, currency exposure, liquidity, investment risks, costs, and estate planning implications may affect their finances before investing.
Tax treatment in your country of residence
Before investing, determine how the relevant jurisdictions treat investment growth, withdrawals, policy proceeds, and foreign-held assets.
Potential tax deferral should not be assumed to apply universally or remain available after relocation.
Currency exposure
Consider the currency of your income, the investment’s denomination, and the currency required for future withdrawals.
Exchange rate movements may affect returns even when the underlying investments perform well.
Liquidity and access to funds
Review minimum withdrawal amounts, partial withdrawal conditions, processing times, and early surrender costs.
Avoid committing funds that may be needed for short-term expenses or emergencies.
Investment and market risk
A portfolio bond can lose value because of risks associated with its underlying investments.
These may include:
- Interest-rate risk
- Credit and default risk
- Equity market volatility
- Inflation risk
- Currency risk
- Illiquidity in alternative investments
An insurance-based structure does not guarantee the performance or safety of the underlying assets.
Costs and net returns
Account for policy and administration fees, investment management expenses, adviser or platform charges, switching costs, and surrender fees.
These costs should be assessed against the expected investment period and projected net returns.
Estate planning and beneficiary arrangements
Portfolio bond proceeds may form part of an estate plan, but beneficiary arrangements must align with applicable inheritance laws.
Review who will receive the policy proceeds, whether beneficiary designations are recognized in relevant jurisdictions, and how the policy interacts with wills and other estate planning documents.
Suitability as circumstances change
Reassess a portfolio bond’s suitability after major changes such as relocation, changes in income or family circumstances, new financial obligations, or a shift in retirement plans.
What are the advantages and disadvantages of portfolio bonds?
Portfolio bonds can give expats access to multiple investments within one insurance-based structure, but their additional fees, tax complexity and restrictions can make them less suitable than simpler investment accounts.
The value of the structure comes from the wrapper around the investments rather than from the portfolio bond generating returns itself. Performance ultimately reflects the underlying assets, applicable charges and any withdrawals.
Potential advantages include:
- Investment flexibility
- Consolidated management
- Potential tax planning benefits
- Fund switching
- Cross-border planning
- Estate planning options
Disadvantages include:
- Layered fees
- Surrender or withdrawal restrictions
- Tax complexity
- Product restrictions
- Investment risk remains
- Ongoing administration
Individual bonds vs portfolio bond structures
Individual bonds provide direct exposure to a specific debt issuer, while international portfolio bonds are insurance-based investment wrappers that allow investors to hold multiple underlying assets within one policy.
|
Feature |
Individual bonds |
International portfolio bonds |
|
Structure |
Debt security issued by a government or company |
Insurance-based investment wrapper |
|
Main purpose |
Lending money to a specific issuer in exchange for interest and potential repayment of principal |
Holding and managing a range of investments within one policy |
|
Investment selection |
Specific government or corporate bonds |
Funds and other assets permitted under the policy |
|
Income |
Coupon payments, if applicable |
Does not automatically pay fixed interest; withdrawals and distributions depend on the policy and underlying investments |
|
Tax treatment |
Interest, capital gains, and maturity proceeds may be taxable under the investor’s local rules |
Investment growth may remain within the policy until a taxable event, subject to local tax rules and policy structure |
|
Liquidity |
Can generally be sold before maturity through a secondary market, although sale prices may be unfavorable or buyers may be limited |
Allows partial or full withdrawals subject to policy conditions, minimum amounts, processing periods, and possible surrender charges |
|
Common access route |
Broker, bank, or bond platform |
Insurance provider or financial adviser |
|
Potential relevance for expats |
May suit investors seeking defined issuer exposure, scheduled interest, or a specific maturity date |
May suit investors seeking consolidated investment management, asset flexibility, and potential policy-based planning benefits |
Conclusion
A portfolio bond should earn its place in an expat’s financial plan by solving a specific problem—not simply by being marketed as an international investment solution.
Its usefulness lies in how well it supports the investor’s broader arrangements, including where assets are held, how wealth is transferred, and how financial decisions are coordinated across borders.
Its benefits are most meaningful when the structure addresses a genuine planning need that simpler investment options cannot meet efficiently.
Without that clear purpose, the additional layers of administration, regulation, and cost may outweigh any perceived advantages.
FAQs
Can a non-US citizen buy bonds?
Yes, non-US citizens can generally buy eligible US bonds, including Treasury securities, subject to brokerage eligibility, account opening requirements, and local regulations.
Access and tax treatment are based on the investor’s country of residence, tax residency, and chosen investment platform.
What is the 5% rule on bonds?
The 5% rule is primarily a UK tax provision for qualifying insurance or investment bonds.
It generally allows annual withdrawals of up to 5% of premiums paid without immediate taxation, although the tax is deferred rather than eliminated.
Which bond gives 12 percent interest?
A bond offering 12% may be available among high-yield corporate or emerging market securities, but the rate may represent either its coupon or market yield.
The actual return depends on the purchase price, issuer’s ability to pay, and risk of default.
Should I have international bonds in my portfolio?
International bonds may be appropriate for expats who need exposure to foreign markets or currencies that match their future financial obligations.
They are not essential for every investor, particularly when currency risk, tax complexity, and investment costs outweigh their diversification benefits.
Related Articles
- Are Offshore Bonds a Good Investment?
- Onshore vs Offshore Investment Bonds: Which Suits Expats?
- What is an international portfolio bond and how does it work?
- Cross-Border Investing for Expats: How to Invest Across Multiple Countries
- Investment Strategies for Expats or People Who Frequently Change Residency