Choosing life insurance as an expat requires checking the amount of coverage needed, the countries where the policy remains valid, the exclusions that apply, and the conditions for paying beneficiaries.
Before buying, expats should compare term and permanent life insurance, understand the insurer’s residency requirements, and establish how a future move could affect coverage.
Key Takeaways
- Coverage should account for dependants, outstanding debts, future expenses, and existing assets.
- International policies require checks on residency eligibility and coverage after relocation.
- Term life suits time-limited needs, while whole life provides lifelong protection and cash value.
- Premiums, payment currencies, and renewal terms determine the long-term cost of maintaining coverage.
My contact details are hello@adamfayed.com and WhatsApp +44-7393-450-837 if you have any questions.
The information in this article is for general guidance only. It does not constitute financial, legal, or tax advice, and is not a recommendation or solicitation to invest. Some facts may have changed since the time of writing.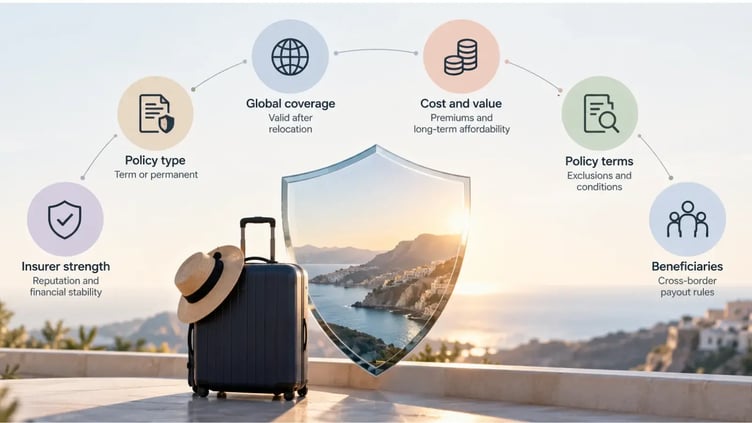
What should you consider before you buy life insurance as an expat?
Expats should assess their financial obligations, coverage needs, residency status, and long-term affordability before buying life insurance.
The following considerations help determine whether a policy provides adequate protection and remains suitable when circumstances change.
Financial responsibilities and dependants
Identify who would face financial hardship if the insured person died.
A spouse, children, dependent parents, or other family members may rely on the insured person's income, while mortgage payments, education costs, and outstanding debts can create obligations that continue after death.
Required coverage amount
Estimate the funds needed to repay debts, replace income, and support dependants, then subtract available savings and existing life insurance benefits.
Account for expenses in different currencies if family members or financial obligations are spread across countries.
Policy type and duration
Decide whether coverage is needed for a defined period, such as until a mortgage is repaid or children become financially independent, or throughout life.
Term and permanent life insurance differ in cost, duration, and potential cash-value features.
Residency and international eligibility
Check whether the insurer accepts applicants living in the intended country of residence and whether nationality, residency status, or other location-related requirements affect eligibility.
An international policy does not automatically guarantee coverage in every country.
Portability after relocation
Confirm whether the policy can remain in force if the insured person moves abroad or changes their country of residence.
Check whether the insurer requires notification and whether relocation could affect premiums, benefits, or policy administration.
Premium affordability
Compare the initial premium, potential future increases, payment frequency, and currency of payment.
Exchange rate movements can make premiums more expensive when income is earned in another currency, so the policy should remain affordable over the intended coverage period.
Exclusions and underwriting conditions
Review restrictions involving medical conditions, high-risk occupations, activities, geographic locations, and other circumstances specified in the contract.
Understand the information required during underwriting and disclose it accurately to reduce the risk of future claim disputes.
Beneficiary arrangements and payouts
Confirm that the intended beneficiaries can be named and understand how they would claim the death benefit.
Consider their country of residence, required documentation, payout currency, and any relevant inheritance or tax implications.
Insurer reliability and claims procedures
Review the insurer's financial strength, regulatory authorization, and process for handling claims involving overseas beneficiaries or documents issued abroad.
Obtain the full policy wording and written clarification of any unclear terms before committing.
The right policy should match the financial protection required, the countries involved, and the budget available over the long term.
Review the contractual terms rather than relying solely on a product brochure, quotation, or verbal explanation from an adviser.
How can I calculate how much life insurance cover I need?
Calculate life insurance coverage by estimating the financial obligations that would remain after death, adding the income support dependants would need, and subtracting resources already available to them.
A practical starting point is to calculate the amount needed to settle debts and fund future expenses.
These may include a mortgage, other loans, children's education, household costs, and financial support for dependants who live in another country.
A Simplified Life Insurance Calculation
Required life insurance cover = outstanding debts + future family expenses + income replacement needs + other financial obligations − available financial resources − existing life insurance.
For example, an expat could estimate the required coverage as follows:
|
Financial requirement |
Illustrative amount |
|
Outstanding mortgage and other debts |
US$150,000 |
|
Future family and education expenses |
US$250,000 |
|
Additional support for dependants |
US$200,000 |
|
Total financial requirements |
US$600,000 |
|
Existing savings available to the family |
−US$100,000 |
|
Existing life insurance |
−US$50,000 |
|
Estimated additional cover needed |
US$450,000 |
These figures are illustrative, not a recommended coverage amount. The calculation should avoid double-counting expenses already included in an income-replacement estimate.
For expats, the calculation may require additional adjustments.
Family expenses might be denominated in a different currency from the insured person's salary, while mortgage payments or education costs may continue in the home country after relocation.
Exchange rate movements can change the amount beneficiaries ultimately receive in purchasing power terms.
The duration of financial support also matters.
A parent with young children may need coverage for longer than someone whose dependants are financially independent.
Existing investments can reduce the required amount, but their liquidity, market risk, and accessibility to beneficiaries should be considered before treating them as available resources.
Revisit the estimate after major changes such as marriage, the birth of a child, purchasing property, taking on substantial debt, or changing countries.
What types of life insurance can expats choose
Expats can choose term life, whole life, universal life, and variable life insurance, subject to insurer eligibility and availability in their country of residence.
They differ in how long coverage lasts, how premiums are structured, and whether the policy builds cash value or offers investment options.
- Term life insurance: Provides coverage for a set period, such as 10, 20, or 30 years. It is generally more affordable than permanent life insurance but usually does not build cash value.
- Whole life insurance: Provides lifelong coverage as long as the policy remains in force, typically with fixed premiums and a cash-value component that grows according to the policy terms.
- Universal life insurance: Offers lifelong coverage with flexible premiums or death benefits under certain conditions. Its cash value may earn interest, and policy charges can affect how long the coverage lasts.
- Variable life insurance: Combines permanent life coverage with investment options for the cash-value component. Returns depend on investment performance, so the cash value may rise or fall.
Is it better to get term or permanent life insurance?
Term life insurance is generally better for affordable coverage over a defined period, while permanent life insurance is better for lifelong protection, provided its higher costs fit your budget.
Term life insurance is often suitable for temporary financial obligations.
Premiums are generally lower than those for permanent coverage with comparable initial death benefits, although pricing depends on the applicant and policy.
Coverage ends when the term expires unless the policy provides an option to renew or extend it.
Whole life premiums are generally higher, and surrendering the policy early may result in a financial loss.
For universal life insurance, policy charges, credited interest, and the amount and timing of premium payments can affect how long coverage remains in force.
A policy with an investment or savings component is not automatically a better financial choice.
Its costs, guarantees, liquidity, and investment risks should be evaluated separately from the value of its insurance protection.
How should expats compare life insurance quotes?
Expats should compare life insurance quotes using the same coverage amount, policy duration and payment frequency, then examine differences in benefits, exclusions and policy conditions.
A lower premium may reflect a shorter coverage period, fewer guarantees or restrictions that make the policy less suitable for your circumstances.
Request a written breakdown showing:
- Whether premiums are guaranteed or can increase.
- Any additional policy fees or optional rider costs.
- How residency changes could affect the policy.
- Whether benefits and premiums are payable in your preferred currency.
- Any differences between the quotation and the terms offered after underwriting.
Compare the final policy terms offered, as the initial quotation may change after the insurer assesses your application.
What not to say when applying for life insurance?
When applying for life insurance, do not conceal or misrepresent information the insurer requests or that is material to the underwriting decision.
Applicants should provide accurate, complete answers about their health, lifestyle, occupation, finances, and residence. Avoid trying to obtain a lower premium by withholding relevant details.
Insurers use application information to assess eligibility and determine the terms on which they will offer coverage.
Incorrect statements or material omissions can lead to higher premiums, changes to the policy, cancellation, or a disputed or denied claim, depending on the circumstances, policy wording, and applicable law.
Particular care is needed when answering questions about:
- Medical history: Disclose requested diagnoses, treatments, medications, and relevant investigations accurately.
- Smoking and alcohol use: Answer questions according to the insurer's definitions and the requested time period.
- Occupation and activities: Describe overseas work, hazardous duties, and high-risk hobbies when requested.
- Travel and residence: State current residency and intended relocation plans accurately, including countries where relevant.
- Existing coverage: Report other policies and previous applications or declined coverage when requested.
- Financial circumstances: Provide truthful information about income, debts, and the purpose of the requested benefit where required.
If a question is unclear, ask the insurer or authorized adviser to explain what it means before submitting the application.
Do not guess, minimize a condition, or rely on an informal assurance that a particular detail is unimportant.
Applicants should also review the completed form before signing.
If an adviser fills it in on their behalf, verify that every answer is correct and that no information has been omitted or altered.
Retain a copy of the application and any supporting documents.
Conclusion
Life insurance is one of those financial arrangements that should work quietly in the background, without requiring the family left behind to untangle a complicated process.
That means thinking beyond the policyholder’s lifetime and considering how easily the intended benefit can translate into financial support across borders.
A useful test is to imagine someone who has never managed the household finances having to deal with the policy alone.
If the purpose of the coverage, the relevant documents, and the claims process would be difficult to understand, the arrangement may need further attention.
FAQs
How do I know if my insurance covers me abroad?
Check the policy wording for territorial restrictions, residency requirements, and conditions relating to overseas travel or relocation.
If the policy was issued before moving abroad, contact the insurer to confirm whether the new country of residence affects coverage or administration.
Is there such a thing as life insurance with living benefits?
Yes, some life insurance policies include living benefits that allow the policyholder to access part of the death benefit while still alive, typically after a qualifying terminal, chronic, or critical illness.
Availability, eligibility requirements, payout limits, and fees depend on the policy and insurer.
What are exclusions in insurance policies?
Exclusions are specific circumstances in which a life insurance policy will not pay benefits or may limit coverage, such as certain pre-existing medical conditions, deaths linked to undisclosed health information, high-risk activities, or suicide during an initial exclusion period.
Check the policy wording for all exclusions and any individual conditions before buying.
What does portability mean in insurance?
Portability refers to the ability to retain or continue insurance coverage when circumstances change, such as moving to another country.
It does not automatically mean that all policy terms remain unchanged.
Related Articles
- How The Wealthy Use Life Insurance to Preserve Wealth
- Understanding Life Insurance for Remote Workers and Expat Travelers
- Can a beneficiary be in another country?
- A Guide to Putting Life Insurance in Trust
- Is Insurance an Investment?
- Insurance Wrapper Explained: How It Works and Why It Matters
- Expat Health Insurance Guide: Choosing the Right International Cover
- Health Insurance for Expat Retirees: How to Choose Your Coverage