Italy’s 26% exit tax proposal would impose tax on unrealized capital gains from certain financial assets when qualifying individuals transfer their tax residence abroad.
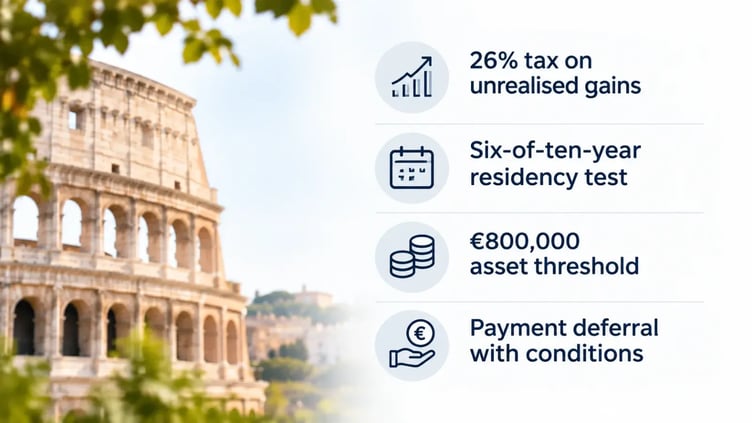
The draft measure, included in Italy’s 2027 Budget Bill, could apply from January 1, 2027, to individuals who meet the six-of-ten-year residency test and hold at least €800,000 in qualifying financial assets.
Key Takeaways
- Italy’s proposed 26% exit tax could still change before any legislation is passed.
- Eligible taxpayers could defer payment, subject to a 50% upfront payment and guarantee.
- Wealthy expats under Italy’s flat tax regime may face additional tax considerations when relocating abroad.
- Italy’s draft would use the previous year-end market value to calculate unrealized gains at departure.
I can connect you with expert tax support for your specific situation. My contact details are hello@adamfayed.com and WhatsApp +44-7393-450-837 if you have any questions.
The information in this article is not tax advice and may have changed since the time of writing.
Does Italy have an exit tax?
Italy already has exit tax rules for businesses and certain entities transferring their tax residence abroad.
Under Article 166 of Italy’s Consolidated Income Tax Act (TUIR), a company’s departure can trigger taxation on unrealized gains from business assets, generally at the 24% IRES rate.
These rules preserve Italy’s right to tax gains accrued while assets or activities were within its tax jurisdiction.
For qualifying transfers to EU or certain EEA countries, payment may be deferred or spread over five annual instalments, subject to the applicable conditions.
However, Italy has not historically imposed a general exit tax on private individuals simply because they move abroad.
Under the existing framework, an individual could generally leave Italy without triggering immediate taxation on unrealized gains from financial investments, provided no other taxable event occurred.
What is Italy’s proposed 26% exit tax?
Italy’s exit tax plan would generally apply at 26% to unrealized capital gains on certain financial assets when individuals transfer their tax residence abroad.
The proposal appears in Article 17 of Italy’s 2027 Budget Bill and could still change before passage.
If enacted as drafted, it would apply where the loss of Italian tax residence takes effect on or after January 1, 2027. The draft also covers certain non-commercial entities.
For individuals, the proposed tax would apply when the following conditions are met:
- Tax residence history: The individual must have been an Italian tax resident for at least six of the ten tax years preceding departure.
- Asset threshold: Qualifying financial assets and rights must have an aggregate fair market value of at least €800,000.
- Loss of Italian taxing rights: Italy must lose its right to tax the relevant gains following the transfer. If it retains those rights under domestic law or an applicable tax treaty, the proposed tax would not apply.
The tax would apply to gains on specified financial assets, including certain shareholdings, securities, financial instruments, derivatives, foreign currencies, precious metals, receivables and crypto-assets.
It would not apply to an individual’s entire net worth, and real estate is generally outside the proposed scope.
Who would be affected by Italy's proposed exit tax?
The proposal could affect long-term Italian tax residents planning to relocate abroad, including expats, international investors and wealthy individuals using Italy’s new-resident flat tax regime.
Certain non-commercial entities, including simple partnerships and qualifying trusts or foundations, could also fall within its scope.
Nationality would not determine liability.
How would Italy’s proposed exit tax affect wealthy expats on the flat tax regime
Wealthy expats using Italy’s new-resident flat tax regime could owe a separate tax on unrealized investment gains when they move their tax residence abroad, even if they keep the investments.
The annual flat tax covers qualifying foreign-source income while they are Italian tax residents.
The draft provides no automatic exit tax exemption for participants.
If they meet the proposed conditions, they could need cash to pay the tax before receiving any proceeds from selling the investments.
How would Italy’s proposed 26% exit tax be calculated?
Italy’s proposed 26% exit tax would be calculated by subtracting the tax cost of qualifying financial assets from their market value at departure, then applying the relevant tax rate to the resulting unrealized gains.
The draft uses the fair market value of the assets on December 31 of the year before departure.
For an individual leaving Italy in 2027, the valuation date would generally be December 31, 2026.
Unrealized losses on other assets would not generally offset taxable gains.
Most qualifying financial assets would be subject to the 26% rate, while Italian government bonds and certain equivalent securities would receive a reduced taxable base of 48.08%, effectively preserving the 12.5% rate.
Example of the Proposed Exit Tax
Consider an investor who meets the residency requirement and relocates abroad in 2027, holding the following qualifying assets:
|
Investment |
Tax cost |
Market value |
|
Shares |
€500,000 |
€800,000 |
|
Investment fund |
€300,000 |
€500,000 |
|
Total |
€800,000 |
€1,300,000 |
The portfolio exceeds the €800,000 asset threshold and has €500,000 in unrealized gains.
Assuming all gains are subject to the 26% rate:
|
Calculation |
Amount |
|
Market value |
€1,300,000 |
|
Tax cost |
€800,000 |
|
Unrealized gains |
€500,000 |
|
Proposed tax rate |
26% |
|
Estimated exit tax |
€130,000 |
This example assumes Italy loses its taxing rights and all assets fall within the proposal.
Actual liability would depend on the final legislation and the assets’ tax treatment.
Because the tax could arise before investments are sold, affected investors may face a substantial payment without having received sale proceeds.
Can Italy’s exit tax be deferred?
Yes. Italy’s proposed exit tax could be deferred for five years for qualifying moves to EU Member States and ten years for moves to other eligible countries, subject to a 50% upfront payment and a guarantee for the remaining liability.
The deferral would not eliminate the tax.
Payment of the balance could be postponed until the relevant investments are sold or another specified event occurs.
Eligible destinations would include:
- Another EU Member State
- A non-EU country that has agreements with Italy for exchanging tax information and collecting outstanding taxes.
The draft also provides for circumstances in which the tax may cease to be due, including when qualifying assets remain unsold until the deferral period ends, pass through inheritance, or the taxpayer returns to Italian tax residence without disposing of them.
Any refund of the upfront payment would be subject to the final rules.
The guarantee requirements, refund procedures and other operational details remain subject to further legislation.
How does Italy’s proposed exit tax compare with other countries?
Italy’s proposal shares a trigger with the French and Canadian exit taxes, losing tax residence can bring certain unrealized gains into tax.
The US expatriation tax instead applies to covered individuals who give up US citizenship or end qualifying long-term permanent residency.
France’s Exit Tax
France’s exit tax can apply when individuals transfer their tax residence abroad.
It generally targets certain unrealized gains on securities and rights, subject to residency and ownership thresholds.
Deferral may be available for qualifying departures, including certain moves within the EU or European Economic Area.
The tax may also lapse in some circumstances if the relevant assets are retained for a specified period.
On October 30, 2026, France’s National Assembly voted for an amendment to the 2027 budget bill that would extend the holding period for exit tax relief from two or five years to 15 years.
If enacted, the change would give taxpayers who retain their covered securities a longer wait for relief.
Like Italy’s proposal, France can tax gains before an investment is sold.
However, the asset scope, eligibility tests, rates and deferral conditions differ.
Canada’s Departure Tax
Canada can tax unrealized gains when individuals cease to be Canadian tax residents. It treats certain assets, such as shares, as if they were sold at fair market value on departure, even if the individual keeps them.
Individuals can elect to defer payment, although the Canada Revenue Agency may require security.
The main difference is the valuation date. Canada generally uses the asset’s value when tax residence ends.
Italy’s draft would use the value at the end of the previous tax year. A rise or fall in the asset’s value between those dates could change the gain used to calculate the tax.
The US Expatriation Tax
Unlike Italy’s proposal, the US tax is triggered by relinquishing citizenship or long-term residency status, rather than simply transferring tax residence abroad.
Known as the exit tax, it generally applies to covered expatriates, determined by criteria including net worth, average income tax liability and tax compliance.
Certain covered expatriates are treated as having sold most of their worldwide assets at fair market value on the day before expatriation, subject to exclusions and exceptions.
Bottom Line
For someone with a long-held portfolio, the cost of leaving Italy could reflect years of investment gains, even if they sell nothing in the year they move.
That gives investors another figure to weigh when comparing destinations. A country may offer lower taxes after the move, while leaving Italy could create a tax bill upfront.
Until the proposal becomes law, however, its final scope and treatment remain unsettled.
FAQs
What is the 7% rule in Italy?
Italy’s 7% tax regime allows eligible foreign pensioners who move to qualifying municipalities in southern Italy to pay a 7% substitute tax on eligible foreign-source income for up to ten tax years.
What taxes do expats pay in Italy?
Italian tax residents generally pay tax on worldwide income, including progressive personal income tax, capital gains tax and applicable property taxes and social security contributions.
Special tax regimes and tax treaties may modify these obligations.
Can you get a tax refund when leaving Italy?
Leaving Italy does not automatically entitle you to a tax refund. However, you may reclaim overpaid taxes.
Under the proposed 26% exit tax, refunds of upfront payments may also be available if qualifying conditions are met.