PHL Variable Insurance Company is expected to enter liquidation proceedings in 2027, but it remains under court-supervised rehabilitation in Connecticut until a liquidation order is issued.
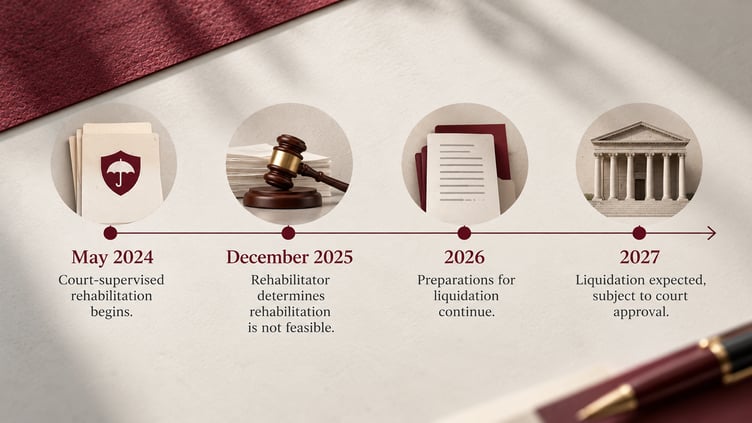
The insurer entered rehabilitation in May 2024, following financial difficulties. In December 2025, the rehabilitator concluded that the company could not be rehabilitated and began preparing for liquidation.
Existing insurance coverage and annuity benefits continue under the current arrangements, although certain payments, withdrawals and policy transactions remain restricted.
If you hold a PHL Variable policy or annuity and would like to hear my thoughts on these developments, or discuss your wider insurance and investment arrangements, email hello@adamfayed.com or WhatsApp +44-7393-450-837.
Why is PHL Variable expected to enter liquidation in 2027?
PHL Variable is expected to enter liquidation because its rehabilitator determined that the insurer could not recover sufficiently to continue under a rehabilitation plan.
The company's financial difficulties led to court-supervised rehabilitation on May 20, 2024, according to the Connecticut Insurance Department.
Rehabilitation is a court-supervised process intended to stabilize an insurer and protect policyholders while its financial condition is assessed.
In December 2025, the rehabilitator concluded that rehabilitation was no longer feasible.
The department subsequently indicated that a transition to liquidation was expected in 2027, although the timing remains uncertain.
Liquidation would involve the court-supervised winding down or transfer of the insurer's obligations, with policyholder protection provided through an acquiring company or applicable state guaranty associations.
Until the court issues a liquidation order, PHL Variable remains in rehabilitation, and existing restrictions continue to apply.
What does PHL Variable's expected liquidation mean for policyholders?
PHL Variable policyholders can generally maintain existing coverage during rehabilitation, but access to benefits and the protection available after liquidation will vary by contract.
The Connecticut Insurance Department confirms that active policies remain in force when required premiums are paid, subject to the court-ordered moratorium.
A moratorium temporarily restricts certain payments and transactions while the insurer's financial obligations are managed.
Several considerations are important for policyholders:
Existing insurance coverage and annuity payments
Insurance claims and scheduled annuity payments continue to be processed subject to the moratorium limits.
Policyholders should continue paying required premiums to maintain coverage.
Withdrawals and policy changes
Certain withdrawals, surrenders, transfers and other transactions remain restricted.
However, some eligible policyholders and annuity holders have received personalized election packages offering options to modify their policies or access funds.
Recipients should review the available choices and comply with the deadlines stated in their packages.
Guaranty association protection
Following liquidation, US policyholders and annuity holders are expected to receive coverage through a buyer or the applicable state life and health insurance guaranty associations, subject to statutory conditions and limits.
The department identifies typical guaranty association limits of $300,000 for life insurance and $250,000 for annuities, although actual protection varies by state and contract.
These limits should not be interpreted as a guaranteed payment or a universal recovery amount.
Potential financial losses
Certain guarantees backed by PHL Variable's general account may not be paid in full.
However, investments held in separate accounts are treated differently, and the rehabilitator does not expect them to be affected by liquidation in the same way.
Before surrendering, replacing or changing a policy, policyholders should check whether they could lose existing guarantees, incur surrender charges or face other financial consequences.
Although liquidation is expected in 2027, it remains unclear when policyholders will receive their payments. The timing and process will depend on further court decisions and updates from the insurer's appointed representatives.