The best way to protect assets from a lawsuit is to combine liability insurance, appropriate ownership structures, and legally available asset exemptions before a claim arises.
No single strategy can make assets completely immune from a lawsuit, so effective protection usually involves several layers tailored to the person's assets and liability risks.
Key Takeaways
- Effective asset protection combines insurance, ownership structures, and available creditor exemptions.
- Asset protection is generally stronger when established before a claim or dispute arises.
- Retirement accounts, primary residences, and certain other assets may qualify for legal creditor protection.
- LLCs, trusts, and other structures do not guarantee that assets are beyond a creditor’s reach.
My contact details are hello@adamfayed.com and WhatsApp +44-7393-450-837 if you have any questions.
The information in this article is for general guidance only. It does not constitute financial, legal, or tax advice, and is not a recommendation or solicitation to invest. Some facts may have changed since the time of writing.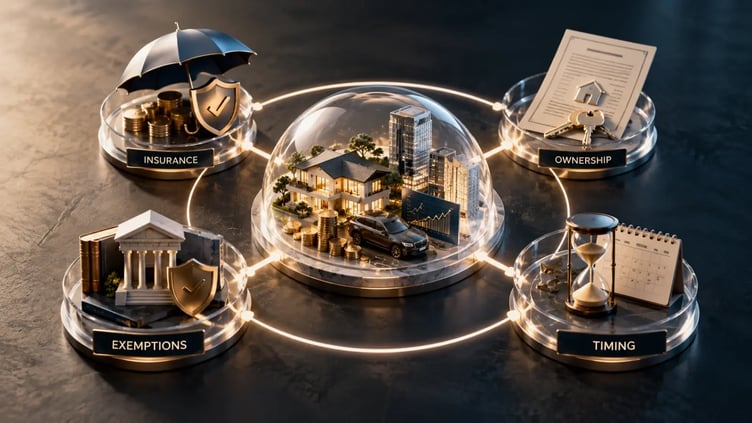
How to protect assets against a lawsuit
The most effective ways to protect assets against a lawsuit are to maintain adequate liability insurance, separate personal and business assets, use legally recognized ownership structures, and take advantage of applicable creditor exemptions.
Each approach protects against lawsuit-related losses in a different way, and the strongest protection typically comes from using several layers together.
1. Liability insurance: Insurance can pay covered legal defense costs, settlements, or judgments up to the policy limits.
This can prevent a covered lawsuit from being paid directly out of the policyholder's personal or business assets.
2. Separate business and personal assets: Operating a business through a properly maintained limited liability company or corporation can keep business liabilities separate from the owner's personal wealth.
If the company is sued over its operations, the claimant will generally have to pursue the company's assets rather than automatically reaching the owner's personally owned property, subject to applicable law and exceptions.
3. Separate high-risk activities from valuable assets: Keeping valuable investments or property separate from businesses and activities that carry greater liability risk can limit the assets exposed to a particular claim.
For example, separating an operating business from unrelated investment assets can prevent a liability arising from the business from automatically putting those investments at risk.
4. Use available asset exemptions: Some jurisdictions protect specific assets or a portion of their value from creditors.
Where applicable, these exemptions can prevent a successful claimant from reaching protected equity or funds, such as qualifying retirement accounts or part of a primary residence.
5. Consider trusts where appropriate: Certain irrevocable or discretionary trusts can place assets under separate legal ownership and restrict the settlor's direct control.
Where the trust is valid and established before a creditor claim arises, this separation can make the assets less accessible to the settlor's personal creditors, subject to the governing law and the terms of the trust.
6. Plan before a claim arises: Establishing protection before litigation is foreseeable gives ownership structures, insurance, and other arrangements time to operate as part of ordinary financial planning.
Transferring assets after a lawsuit or creditor claim has emerged may instead expose the transfer to challenges as a fraudulent or voidable transaction.
These measures do not make assets immune from lawsuits.
Their purpose is to limit the assets exposed to a particular liability, provide funds to meet covered claims, or place assets within legal protections recognized by the relevant jurisdiction.
What happens to your assets when you are sued?
When a person is sued, assets are not automatically taken, but a successful judgment can allow a creditor to pursue property that is legally available to satisfy the debt.
The assets exposed to enforcement are shaped by the nature of the claim, the applicable law, and the ownership of the property.
Depending on the jurisdiction, enforcement may reach bank accounts, investments, real estate, business interests, income, or other property.
A key distinction is whether assets belong to the defendant personally or to a separate legal entity.
Personal assets may be exposed when the individual is personally liable for the judgment, while assets belonging to a separate entity are generally subject to different rules.
What assets are safe from lawsuits?
Assets that may have protection from lawsuits include qualifying retirement accounts, certain primary residences, some life insurance and annuity benefits, essential personal property, and assets covered by specific creditor protection laws.
The exact protection varies by jurisdiction, the type of claim, and the legal status of the asset.
In the US, for example, bankruptcy law allows certain property to be treated as exempt, while individual states may have their own exemption rules.
Similar protections exist in other jurisdictions, although the assets covered and the level of protection can differ significantly.
Potentially protected assets can include:
- Retirement and pension assets: Certain accounts may receive statutory protection from creditors.
- Primary residences: Some jurisdictions protect all or part of the equity in a qualifying home.
- Life insurance and annuities: Certain policies or benefits may receive creditor protection under local law.
- Essential personal property: Items considered necessary for basic living may qualify for exemptions.
- Work-related assets: Tools, equipment, or other property required for an occupation may receive limited protection.
- Assets held under protected structures: Certain trusts or other legal arrangements can place assets within a separate legal framework that may restrict creditor access.
These protections are not automatic or unlimited.
Exemptions can have value limits, eligibility requirements, and exceptions for particular types of creditors or claims.
What assets can you lose in a lawsuit?
Assets that can potentially be exposed to a successful lawsuit include cash, investment accounts, real estate, vehicles, business interests, and other property that is legally available to satisfy a judgment.
Assets held directly in an individual's name can be easier to identify as part of that individual's wealth than assets owned by a separate legal entity.
Real estate can be particularly significant because it is relatively easy to identify and is governed heavily by the law of the jurisdiction where the property is located.
A creditor may also have different enforcement options depending on whether the property is a primary residence, investment property, or commercial property.
Business ownership interests can create another area of exposure.
A lawsuit against an individual does not necessarily give a claimant unrestricted access to company assets, just as a lawsuit against a properly structured company does not necessarily make the owner's personal assets available.
The separation can be weakened, however, by factors such as personal guarantees, commingling of funds, failure to maintain corporate formalities, or using a company as though it were simply a personal bank account.
When asset protection measures may be too late
Asset protection measures may be too late when a person already knows about a creditor claim, lawsuit, judgment, insolvency problem, or other foreseeable liability and attempts to move assets specifically to prevent the creditor from reaching them.
This is one of the most important distinctions between proactive asset protection and reactive asset concealment.
A transfer that occurs before any dispute exists may form part of legitimate estate or wealth planning.
A transfer made after a claim arises can receive much greater scrutiny.
Timing can therefore affect the effectiveness of:
- Transfers to trusts
- Transfers to companies
- Gifts to family members
- Changes in property ownership
- Transfers to offshore structures
- Asset sales involving related parties
Conclusion
The real measure of asset protection is not how complicated the structure looks, but how well it holds up when circumstances change.
A strategy that works on paper can become ineffective if ownership arrangements, insurance coverage, tax obligations, or legal requirements are no longer aligned with the underlying assets.
Asset protection should be treated as an ongoing part of wealth management rather than a one-time legal arrangement.
Periodic reviews can identify gaps created by new investments, business ventures, property purchases, changes in residence, or shifts in liability exposure before those gaps become costly.
FAQs
What type of insurance can I get to protect my assets?
Common types include homeowners or renters liability insurance, auto liability insurance, professional liability insurance, business liability insurance, and umbrella or excess liability insurance.
These policies can cover eligible claims, legal costs, settlements, or judgments, reducing the amount that may have to be paid from personal or business assets.
What is the best way to protect your home from a lawsuit?
A primary residence may receive protection through a homestead or other statutory exemption, while appropriate homeowners liability insurance can cover certain claims involving the property.
Are retirement accounts subject to lawsuits?
Some retirement and pension accounts receive statutory protection from creditors, while others may be exposed to claims.
The applicable protection hinges on the account type, jurisdiction, and nature of the creditor's claim.
What is the most expensive asset protection tool?
Complex international trust structures can be among the most expensive asset protection arrangements because they may involve trustees, legal and tax advisers, corporate entities, and ongoing administration.
Costs vary significantly based on the structure, jurisdiction, and value of the assets involved.
Related Articles
- How Can High-Net-Worth Individuals Protect Their Assets?
- Can PPLI Protect Your Assets? How Private Placement Life Insurance Works
- Trusts and Asset Protection Strategies for Expats
- How to Preserve Wealth
- Prenup vs Offshore Trust: Which is Better for Wealth Protection?
- Can an Offshore Trust Protect Assets in Divorce? The Complete Answer
- Offshore Asset Protection Countries Compared: Where to Protect Your Wealth