The RL360 Regular Savings Plan offers access to investment funds through a long-term savings policy, but its restrictive structure deserves close attention. Fund choice is only part of the picture.
Investors also need to consider the cost of leaving early and the limitations on changing contributions or accessing their money.
My contact details are hello@adamfayed.com and WhatsApp +44-7393-450-837 if you have any questions. This includes if you have a policy and aren’t happy.
Some of the facts might change from the time of writing, and nothing written here is formal advice. So, potential investors shouldn’t invest or decide not to invest based on this review alone.
Who is RL360?
Isle of Man-based RL360 is a firm that specializes in providing expats and local residents located in a variety of countries across the globe with offshore savings, protection, and investment solutions.
The company has operations around the globe. This includes Asia, the Middle East, Africa, and the United Kingdom.
RL360 is a subsidiary of International Financial Group Limited (IFGL).
What to Know About the RL360 Regular Savings Plan
The RL360 Regular Savings Plan is a long-term investment policy available to applicants aged 18 to 65, subject to eligibility requirements.
It offers seven plan currencies: US dollars, euros, British pounds, Australian dollars, Swiss francs, Hong Kong dollars and Japanese yen.
Investors commit to regular contributions over a chosen payment term. The plan can be used to build funds for retirement or education, but that commitment can become restrictive if income falls, circumstances change or access to savings becomes a priority.
A payment holiday of up to two years is available only after the establishment period and subject to minimum plan value requirements. Charges continue during the break, and the servicing charge increases.
Withdrawals are also restricted. During the payment term, they can only come from standard units after the establishment period, with the remaining plan value above the required minimum.
The RL360 Regular Savings Plan requires a commitment that may become difficult to maintain if your circumstances change.
Choosing an affordable contribution today does not guarantee that it will remain affordable after a job loss, relocation or change in family responsibilities.
Although the plan offers fund switching and some payment adjustments, these features should not be confused with unrestricted control over your savings.
The ability to change investments within a policy does little to resolve the financial consequences of needing to leave it.
For expats, this structure can become a burden when a relocation, career break or unexpected expense changes what they can afford.
Choosing a contribution that suits your finances today means little if maintaining it becomes difficult later.
The concern is whether the plan leaves enough room to adapt without a substantial financial setback.
What are the contribution minimums?
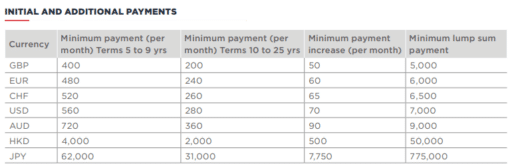
For monthly contributions, you are required to pay a minimum of 280 USD per month into your plan. You can top up anytime you wish to.
In addition to regular monthly contributions, RL360 Regular Savings Plan also allows for lump sum payments. The minimum amount for such payments is 7,000 USD.
The savings terms for the RL360 Regular Savings Plan are flexible, ranging from 5 to 25 years, and the minimum contribution varies depending on the term length.
For example, the minimum payment per month for terms between 5 and 9 years is 400 GBP, while it’s 200 GBP for terms that are more than 10 years.
Below is a table of for all seven currencies offered and the payment requirements:
Customers can make contributions via direct debit, bank transfer, or even credit card.
Each time you make a regular payment into the RL360 Regular Savings Plan, the full amount will be used to invest in the chosen funds. In some cases, for larger payments, RL360 may increase the allocation to 101% or 102%.
What about investment minimums?
The minimum sums required to be invested in the various funds offered by the Plan change based on the currency being used.
For investments in GBP, the minimum amount is 25, while for those made in USD, EUR, CHF, or AUD, the minimum amount is 50. Fund investments denominated in HKD or JPY should be at least 500 or 5,000, respectively.
What are the charges?
Standard Costs
First, during the payment term, the value of the establishment units in your plan will be reduced by 0.50% per month to account for the establishment charge.
In addition, both the establishment and the standard units share equally in the continuous administration fee of 0.125% of the current plan value.
The standard units in the scheme will also have a monthly service fee subtracted from them. This fee now stands at 5 pounds (or its equivalent in other currencies) and will grow annually by the percentage change in the Retail Price Index for the Isle of Man.
In addition, the plan’s assets will incur a management fee of 0.5% to 2% every year.
RL360 does not charge clients who opt to pay into their policy via credit cards. However, 1% of the payment sum is assessed for those who specifically use American Express credit card.
On the other hand, you can benefit from zero charges when you first invest in any of the funds available, as well as for any future investments you make.
RL360 Regular Savings Plan also allows you to switch the funds you invest in without any extra charges.
You can make changes to meet your financial goals without being penalized. Additionally, unlike other offshore products, you do not have to worry about custodian fees.
Optional Fees
The investment advisor fee and the financial adviser fee are two examples of discretionary charges that could be assessed too.
In exchange for their services, investors pay investment advisers fees, which may be made either directly by the investor or via RL360.
However, investors and their financial advisors need to come to terms on how much the advisor will be paid.
RL360 will deduct the agreed upon amount from the plan and send it straight to the financial advisor if the investor agrees to pay a fee to the advice.
Can I get discounts or incentives?
Yes, but is quite possible that the amount of the bonus awarded to each individual consumer will be unique. Customers get bonuses based on their savings level, plan duration, plan age, and full-year contributions.
RL360 offers a starter bonus of up to 600% of the monthly payment when you begin the plan.
There is also a loyalty bonus calculated using the total worth of your assets at the conclusion of the payment period, rather than being tied to the initial sum invested. This indicates that your bonus might increase based on the plan’s success.
Bonuses tend to increase over time if a plan is kept in place and payments are continued.
Customers are permitted to invest in an unlimited number of funds, provided that they keep their monthly contribution to each fund at a minimum of 25 pounds (or its local currency equivalent).
Is the RL360 Savings Plan safe?
The plan is managed by the Isle of Man Financial Services Authority, so policyholders may get 90% of their money back if the unthinkable happens and their life insurance firm goes bankrupt.
To further safeguard policyholder funds, the Insurance Act of 2008 requires all insurance firms operating on the Isle of Man to secure all policyholder assets.
Most people who invest their money want to put it somewhere safe, tax-friendly, and promising of high returns. Putting your money in a local bank account or any alternative investments is always an option.
Are there tax considerations?
There is a substantial tax benefit for having an RL360 Regular Savings Plan. Your policy’s gains and dividends will be free from taxation in the Isle of Man, where the firm is headquartered.
With the exception of withholding taxes that may be collected at source on income flowing from assets held in specific countries and cannot be recovered by the firm, your investment will grow free of any additional deduction of Isle of Man tax.
Can I get a refund if I terminate my Regular Savings Plan early?
If you terminate the plan within 30 days of starting it, you’ll receive your original money back unless of course if the value of the assets you invested in has plunged.
A 100% early departure penalty will be assessed if you cancel the plan after the 30-day cooling off phase but before the end of the establishment term.
If the plan is terminated after the establishment period, only the early exit fee on the establishment units will be assessed. Cancelling the plan before its term is over might result in a significant loss of savings.
During the setup phase, all payments are applied to the initial unit purchase price. Once the initial payment period ends, the funds will be applied to standard units.
Any unused establishment units at the conclusion of your plan period will automatically be converted to standard units.
After the plan’s setup period ends, you can start taking withdrawals on a monthly, quarterly, semiannual, or annual basis. It is also possible to make a one-time withdrawal.
RL360 Regular Savings Plan Review: Final Thoughts
The RL360 Regular Savings Plan’s main drawback is the financial cost of changing course before the agreed payment term ends.
RL360’s published literature confirms that establishment units remain subject to an early exit charge if the plan is cancelled before the payment term finishes. Completing the initial establishment period therefore does not remove the cost of leaving early.
This is a serious limitation for expats. Employment, residency and family commitments can change considerably over a long savings term.
A policy that becomes expensive to exit can leave investors maintaining an arrangement that no longer suits their needs.
Access to a broad fund range and free fund switching does not, in my view, adequately compensate for that loss of flexibility.
If you already hold a policy, obtain an up-to-date surrender value and compare the consequences of continuing, reducing payments or exiting. A restrictive product can be a poor fit, but leaving without checking the figures can compound the loss.