Offshore investment bonds are insurance-based investment wrappers that can hold funds, equities, bonds, and other permitted assets within a single policy.
Offshore investment bonds may support portfolio consolidation, long-term investment management, and succession planning, but their usefulness depends on the policy structure, investment options, costs, liquidity, and the investor’s tax residence.
Key Takeaways
- Offshore investment bonds combine insurance with access to permitted investments.
- Their structure varies by premiums, ownership, withdrawals, segmentation, and currency.
- Bond types and products differ in investment flexibility and wealth planning features.
- Expats should compare tax, costs, investment options, liquidity, portability, and provider protection.
My contact details are hello@adamfayed.com and WhatsApp +44-7393-450-837 if you have any questions.
The information in this article is for general guidance only. It does not constitute financial, legal, or tax advice, and is not a recommendation or solicitation to invest. Some facts may have changed since the time of writing.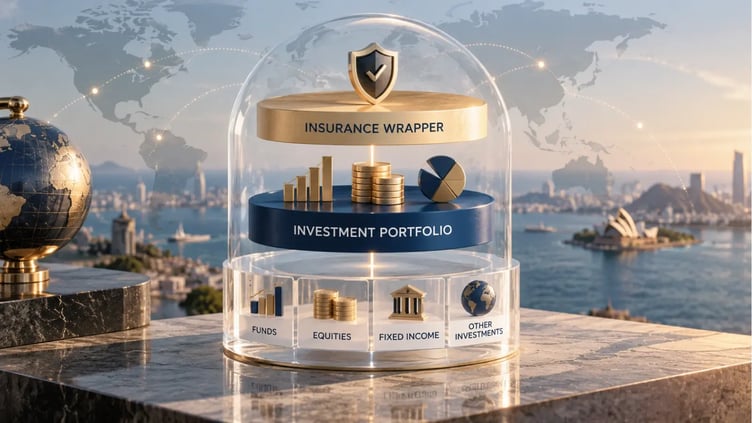
What are offshore investment bonds?
Offshore investment bonds are life assurance or capital redemption investment wrappers issued through insurance companies in jurisdictions outside an investor's country of residence.
They typically hold underlying investments such as mutual funds, equities, bonds, and other permitted assets.
The three layers of an offshore investment bond
1. The insurer
The insurance company issues the bond/policy.
2. The bond wrapper
The policy provides the legal and administrative structure around the investment.
3. The underlying investments
The policy can hold permitted funds, equities, bonds, portfolios or other investments.
Despite the name, an offshore investment bond is not the same as purchasing a corporate or government bond issued overseas.
How are offshore investment bonds structured?
Offshore investment bonds can be structured around different ownership arrangements, premium types, policy segments, withdrawal options, and succession features.
These structural differences can affect how the policy is managed, accessed, transferred, and taxed.
Single-Premium and Regular-Premium Structures
Offshore investment bonds can be funded through a single lump-sum premium or, where the product allows it, through additional or recurring contributions.
A single-premium structure is common for investors placing a substantial amount into a long-term investment wrapper.
Products that accept additional premiums can provide greater flexibility for investors who expect to add capital over time.
Minimum premiums and rules for subsequent contributions vary between products.
An expat's country of residence can also affect whether additional contributions remain available after relocation.
Segmented Bond Structures
Some investment bonds are divided into multiple policy segments rather than being treated as one single contract.
Each segment represents part of the overall policy value.
Segmentation can provide greater flexibility when only part of the investment needs to be withdrawn, assigned, or transferred.
Instead of terminating the entire policy, the investor may be able to deal with individual segments, subject to the policy terms and local tax rules.
This can be particularly relevant when planning withdrawals over several years, although the tax treatment of a segment depends on the investor's country of residence.
Individual, Joint and Trust Ownership
The policyholder is the person or entity that owns the bond and holds the contractual rights under the policy.
Depending on the product and jurisdiction, ownership may be available to an individual, joint policyholders, or a trust.
Ownership can affect who controls the policy, who receives its benefits, and how the investment is treated for estate and tax purposes.
Trust ownership can introduce additional succession planning possibilities, but it also creates separate legal, tax and reporting considerations.
A trust does not automatically make an investment bond exempt from taxation or inheritance rules.
Life Assured and Beneficiary Arrangements
Investment bonds can also include a life assured, whose death may trigger the payment of a death benefit under the policy.
Some policies allow beneficiaries to be nominated or policy rights to be assigned.
These features can help determine how the bond passes to another person following death or during the policyholder's lifetime.
The actual outcome depends on the policy terms and the succession, inheritance and tax rules that apply in the relevant jurisdiction.
Withdrawal and Surrender Structures
Offshore investment bonds can provide access to capital through partial withdrawals, full surrender, or other methods specified by the policy.
The structure matters because accessing part of the investment does not necessarily have the same consequences as terminating the entire policy.
Minimum withdrawal amounts, remaining policy values, surrender charges, and other conditions can apply.
For expats, these rules should be considered alongside the tax treatment of withdrawals in the country of residence.
Policy Currency
Some offshore investment bonds can be established in different currencies, commonly including USD, GBP and EUR.
The available currencies depend on the specific product and insurer.
The policy currency can affect how contributions, withdrawals and investment values are recorded, but it does not remove foreign exchange risk.
An investor who earns income or expects future expenses in a different currency may still be exposed to exchange rate movements.
What are the different types of offshore investment bonds?
The main types of offshore investment bonds include standard investment bonds, portfolio bonds, and products designed around specific investment or wealth planning requirements.
Standard Offshore Investment Bonds
Standard offshore investment bonds provide a relatively straightforward way to hold a range of permitted investments within an insurance-based investment product.
They are generally designed for investors who want a structured investment vehicle without requiring the broader investment capabilities of a portfolio-oriented bond.
The available funds and investment options vary between products, so a standard bond can still provide diversified exposure across different asset classes.
Portfolio Bonds
Portfolio bonds are designed for investors who require broader investment choice or greater control over how a portfolio is constructed within the policy.
Depending on the product, the investment menu may extend beyond conventional funds to include a wider range of portfolios, securities, or other permitted investments.
This can make portfolio bonds more suitable for investors with more specific asset allocation requirements, although greater choice can also introduce additional investment and management complexity.
Investment Bonds With Broader Wealth Planning Features
Some offshore investment bonds incorporate features intended to support wider wealth planning objectives alongside investment management.
These can include beneficiary arrangements, assignment options, or features that may be used alongside estate planning structures.
The presence of these features does not make a product automatically more suitable for estate planning.
Examples of offshore investment bond products for expats
Offshore investment bond products such as Utmost Wealth Solutions, RL360 Oracle and PIMS, Canada Life International bonds, and Friends Provident International Reserve illustrate the different structures available to expats.
Utmost Wealth Solutions investment bonds
Utmost Wealth Solutions offers international investment bond products with portfolio-based structures, access to different investment options, and features such as additional contributions and beneficiary arrangements.
Certain Evolution policies require minimum investments of £50,000 or US$100,000, depending on the policy and currency.
RL360 Oracle and PIMS
RL360 offers two products that illustrate different levels of investment flexibility.
Oracle provides a simpler investment bond structure, while PIMS is a portfolio bond with broader investment choices.
Minimum investments, withdrawals, and charges vary between the products.
Canada Life International investment bonds
Canada Life International offers investment bonds designed for long-term wealth management, with portfolio-based investment opportunities and features supporting estate and succession planning.
Product availability and investment options vary by jurisdiction and policy.
The insurance-based structure may also include surrender restrictions or charges for investors who access their capital early.
Friends Provident International Reserve
Friends Provident International Reserve is designed for lump-sum investors seeking long-term capital growth and regular withdrawals.
It has a £50,000 minimum investment and a suggested five-year investment period, while availability and policy terms vary by jurisdiction.
How to choose the best offshore investment bond
Choosing the best offshore investment bond requires comparing its tax treatment, costs, investment flexibility, and suitability for your current and future countries of residence.
Expats should consider the following factors before investing.
1. Tax Treatment in Your Country of Residence
Your tax residency determines how investment growth, withdrawals, and policy gains are treated.
Tax deferral available in one jurisdiction may not apply elsewhere.
Check how your country of residence taxes offshore bonds and whether reporting obligations apply.
2. Investment Options and Flexibility
Review the underlying investments available through the policy, which may include:
- Mutual and equity funds
- Fixed-income funds
- Multi-asset portfolios
- Structured investments
Choose a product that supports your preferred asset allocation without adding unnecessary complexity.
3. Fees and Charges
Compare the bond’s total costs, including:
|
Fee |
What to Check |
|
Policy and administration fees |
Ongoing insurance and account charges |
|
Fund management fees |
Costs charged by underlying investments |
|
Adviser fees |
Financial planning or portfolio management charges |
|
Withdrawal and surrender charges |
Costs of accessing funds or ending the policy early |
|
Currency conversion fees |
Costs of managing investments in different currencies |
High cumulative charges can reduce long-term returns, even when investment choices are extensive.
4. Minimum Investment Requirements
Compare the product’s:
- Minimum initial premium
- Additional contribution requirements
- Minimum withdrawal amount
- Minimum remaining policy value
Requirements vary by product, so expats should avoid assuming that every offshore bond requires substantial seven-figure capital.
5. Portability After Relocation
Confirm whether the policy can remain active if you:
- Move to another country
- Change tax residency
- Retire overseas
- Return to your home country
Although the bond may remain valid after relocation, its tax treatment, reporting requirements, and available features may change.
6. Provider Regulation and Financial Strength
Review the issuing insurer’s regulatory authorization, financial strength, and policyholder protection arrangements.
Also check the relevant complaints process and the legal entity issuing your policy.
An offshore structure does not automatically indicate higher risk, but regulation does not eliminate investment or provider-related risks.
What are the benefits of offshore investment bonds for expats?
The potential benefits of offshore investment bonds for expats include tax deferral, international investment access, portfolio consolidation, estate planning features, and multi-currency options.
Potential Tax Deferral
In some jurisdictions, investment growth within an offshore bond may not be taxed immediately, allowing returns to remain invested without annual taxable disposals.
However, withdrawals, maturity, or changes in tax residency may trigger tax liabilities.
International Investment Access
Offshore bonds can provide access to international funds and asset classes within an insurance-based structure, allowing expats to hold and manage investments across different markets.
Portfolio Consolidation
Multiple investments can be held within a single policy, potentially simplifying portfolio administration, investment switching, and consolidated reporting.
Estate and Succession Planning
Certain policies offer beneficiary nomination, assignment, or trust-related features that can help structure the transfer of wealth.
These features do not automatically eliminate inheritance tax or probate requirements, which remain subject to applicable local laws.
Multi-Currency Investment Opportunities
Multi-currency options can allow expats to hold investments in currencies aligned with their income, assets, or future expenses.
They do not, however, eliminate foreign exchange risk.
What are the disadvantages of offshore investment bonds for expats?
The disadvantages of offshore investment bonds for expats include complex cross-border taxation, layered fees, limited liquidity, market and currency risk, and provider or jurisdiction risk.
Complex Cross-Border Taxation
Tax treatment can change when an expat relocates.
Policy gains, withdrawals, assignments, and foreign asset reporting may be subject to different rules in each country.
Tax treatment in the country where the bond was issued may also differ from the rules in the investor’s country of tax residence.
Potentially High Fees
Policy charges, fund expenses, and adviser fees can reduce net returns over time.
The total cost should be considered alongside the investment options and other features offered by the policy.
Limited Liquidity
Withdrawals may be subject to minimum amounts, policy conditions, or surrender charges.
These restrictions can make some offshore bonds less suitable for investors who require frequent or immediate access to their capital.
Market and Currency Risk
Returns depend on the underlying investments, which can lose value because of market movements, interest rate changes, or currency fluctuations.
Holding investments through an offshore bond does not guarantee capital preservation.
Provider and Jurisdiction Risk
The issuing insurer’s financial strength, regulatory framework, and available policyholder protections vary by jurisdiction.
The level of protection available to policyholders can differ between offshore bond providers and the jurisdictions in which they operate.
Offshore investment bonds vs other expat investment options
Offshore investment bonds combine investment management with insurance-based wealth planning features, while other expat investment options generally provide greater liquidity, direct investment control, or more predictable income.
Expats should compare these options based on their investment objectives, tax residency, liquidity requirements, and desired control over assets.
|
Investment Option |
Most Suited For |
Main Advantages |
Key Considerations |
|
Offshore investment bonds |
Expats seeking structured investment management and wealth-planning features |
Potential tax planning, portfolio consolidation, and beneficiary arrangements |
Fees, tax complexity, and withdrawal restrictions |
|
International brokerage accounts |
Investors wanting direct control over securities and portfolio construction |
Broad investment access and flexibility |
Tax reporting, transaction costs, and limited insurance-wrapper features |
|
International mutual funds |
Investors seeking diversified exposure with professional management |
Diversification and convenience |
Fund expenses and limited control over individual holdings |
|
Offshore savings accounts |
Expats prioritizing liquidity and capital accessibility |
Easy access to cash and lower market exposure |
Inflation risk and potentially limited investment growth |
|
Government and corporate bonds |
Investors seeking interest income or defined maturity dates |
Potential coupon income and repayment at maturity |
Credit, interest rate, and currency risks |
Conclusion
Offshore investment bonds can be useful for expats when the insurance-based structure solves a specific cross-border planning need that would be difficult to achieve through a simpler investment account.
The key consideration is not how many features a bond offers, but whether those features justify the additional costs, restrictions, and tax complexity.
A policy with extensive investment choice may still be inefficient if the underlying funds are expensive or the structure limits access to capital.
For expats, the strongest case for an offshore bond is usually created when its investment, succession, currency, and administrative features work together to address a long-term need.
FAQs
How are withdrawals from an offshore bond taxed?
Withdrawals are taxed according to the investor’s country of tax residence, the policy structure, and the applicable local rules.
They may be subject to tax on investment gains or other income, so offshore withdrawals are not automatically tax-free.
Which currency is commonly used for international bond issues?
The US dollar is one of the most common currencies for international bond issuance, alongside the euro and other major currencies.
Offshore investment bonds may also be denominated in currencies such as GBP, USD, or EUR, depending on the provider and policy.
What happens to bonds if a company goes bankrupt?
If a corporate bond issuer goes bankrupt, bondholders may lose interest payments and some or all of their principal.
For an offshore investment bond, the outcome depends on the insurer’s solvency, policyholder protections, and performance of the underlying investments.
What happens to an investment bond when someone dies?
When the policyholder or life assured dies, the bond may pay a death benefit or transfer its value to beneficiaries or the estate, according to the policy terms.
Tax and inheritance implications are shaped by the policy structure, ownership arrangements, beneficiary designations, and applicable local laws.
Related Articles
- Offshore Explained: An Offshore Guide
- How to Buy Portfolio Bonds for Expats
- 5% rule on portfolio bonds explained for expats
- Why Have Bonds In Your Portfolio
- Investing in Portuguese Corporate Bonds: Income, Risks and Tax
- How to Invest as an Expat: A Practical Framework for Building a Global Portfolio
- Expat Investment Advice for International Tax Planning: Guide to Tax-Efficient Global Investing
- Top Offshore Investments in 2026: Best Assets, Jurisdictions, & Risks to Know