International health insurance costs can range from several hundred dollars to more than US$10,000 per year for individual expats, based on the level of coverage and personal circumstances.
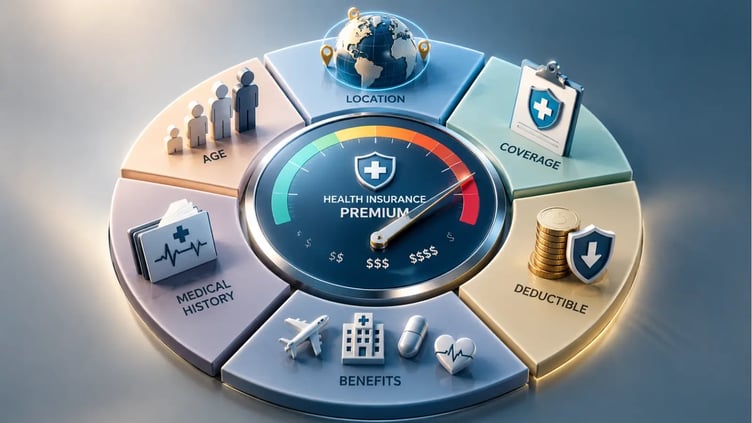
Age, country of residence, medical history, geographical coverage, deductible and selected benefits are among the main factors that determine the premium.
Key Takeaways
- Exclusions, pre-existing conditions and benefit limits can affect how much a policy pays.
- Comparing deductibles, coverage areas and benefits helps reveal the true cost of a policy.
- US-inclusive worldwide coverage generally costs more than coverage excluding the US.
- Higher deductibles and fewer optional benefits can lower premiums.
My contact details are hello@adamfayed.com and WhatsApp +44-7393-450-837 if you have any questions.
The information in this article is for general guidance only. It does not constitute financial, legal, or tax advice, and is not a recommendation or solicitation to invest. Some facts may have changed since the time of writing.
How much does international health insurance cost for expats?
International health insurance for expats can cost roughly US$1,000 to US$5,000 or more per year for an individual, although premiums can fall below or rise substantially above this range based on the policy.
Comprehensive plans with extensive worldwide coverage, particularly those including the US, can exceed US$10,000 annually.
Insurers calculate premiums based on the insured person's circumstances and the benefits selected.
Allianz, for example, identifies age, country of residence, destination countries, number of members, coverage level, pre-existing conditions and medical history among the factors used to determine cost.
As a general illustration, published market examples show that a relatively basic international plan can start at several hundred dollars per year, while more comprehensive cover can move into several thousand dollars annually.
A plan with inpatient and outpatient treatment, wider geographical coverage and additional benefits will generally cost more than an inpatient-only policy.
International Health Insurance Cost by Coverage Level
|
Coverage type |
Indicative annual cost |
Typical characteristics |
|
Basic international cover |
From around US$500 |
Limited benefits and/or higher excess |
|
Standard comprehensive cover |
Around US$1,500–US$5,000+ |
Hospital and broader medical benefits |
|
Premium comprehensive cover |
US$5,000–US$10,000+ |
Wider benefits and geographical coverage |
|
High-end worldwide cover |
US$10,000+ |
Extensive benefits, potentially including the US |
How much does international health insurance cost by country?
International health insurance costs vary significantly by country because insurers account for local private healthcare costs when setting premiums.
The SIP Health Cost Index 2026 compared standardized international private medical insurance profiles across major healthcare markets. Its five highest-cost markets were:
|
Country |
Average annual IPMI-based cost |
|
United States |
US$23,987 |
|
Hong Kong |
US$19,353 |
|
Singapore |
US$17,613 |
|
China |
US$15,235 |
|
United Kingdom |
US$14,987 |
These figures are comparative market benchmarks rather than typical premiums for every expat. Actual quotes vary according to age, benefits, deductible, medical history and other individual factors.
The country ranking nevertheless shows why location can materially affect international health insurance costs.
An expat moving between countries may face a different premium even without substantially changing the benefits included in the policy.
Countries with higher private medical costs can produce higher international insurance premiums, and US-inclusive coverage is particularly expensive.
What are some factors that affect the cost of international health insurance?
Age, country of residence, geographical coverage, medical history, deductible and selected benefits are the main factors that affect the cost of international health insurance.
How does age affect international health insurance costs?
International health insurance generally becomes more expensive with age as expected healthcare use and claims costs increase.
The difference can become substantial across older age bands, even when the underlying plan and deductible remain the same.
This is particularly relevant when planning health insurance for expat retirement , as premiums may take up a larger share of the retirement budget over time. Changing insurer at an older age can also become more difficult if a new policy has maximum entry ages or requires fresh medical underwriting.
Age should therefore be considered alongside renewal terms and future premium increases when comparing long-term coverage.
Country of Residence
The SIP Health Cost Index 2026, which compared standardized international private medical insurance costs across 50 countries, placed the US at the highest average cost among the countries in its ranking.
Hong Kong, Singapore, China and the UK also had relatively high average costs.
The relationship is not always straightforward, however.
A country with relatively low general living costs can still have expensive private healthcare for internationally insured patients.
Geographical Area of Coverage
An insurer may offer options such as:
- A specific country or region
- Europe
- Asia
- Worldwide excluding the US
- Worldwide including the US
Worldwide coverage provides greater flexibility but can cost more.
Removing the US from worldwide coverage can reduce the premium where the insurer offers that option because US healthcare costs are particularly high.
Global insurers, for example, offer different geographical areas of cover, including worldwide and worldwide excluding the US.
Level of Coverage
A policy covering only major hospitalization costs will generally have a different price from a comprehensive plan covering hospitalization, outpatient consultations, diagnostics, prescription medication and other services.
Some international policies use a modular structure, allowing customers to select additional benefits.
Deductible or Excess
A deductible, sometimes called an excess, is the amount you agree to pay toward eligible medical expenses before the insurer pays according to the policy terms.
Choosing a higher deductible can reduce the premium because you are retaining more of the initial healthcare cost yourself.
This can make sense for an expat who wants insurance primarily for substantial medical expenses rather than routine healthcare.
The trade-off is that you will have greater out-of-pocket costs when making eligible claims.
Pre-Existing Conditions and Medical History
Medical history can affect both eligibility and pricing. Pre-existing conditions are not handled identically by every insurer.
Depending on the underwriting method and policy, they may be covered, excluded or subject to specific conditions.
Number of People Insured
Adding a spouse or children increases the total premium because each person is insured.
However, the cost is not simply determined by multiplying one person's premium by the number of family members.
Each insured person's age and circumstances can affect their individual premium.
Optional Benefits
Optional benefits can also increase the overall cost of a policy. These can include:
- Outpatient treatment
- Dental care
- Optical care
- Maternity
- Preventive care
- Mental health treatment
- Medical evacuation
- Additional wellness services
What does international health insurance cover?
International health insurance can cover inpatient and outpatient treatment, emergency care, specialist consultations, diagnostic tests, prescription medication and other eligible medical expenses, based on the policy.
- Inpatient care: Hospitalization, surgery and medically necessary hospital treatment.
- Outpatient care: Doctor and specialist consultations, diagnostics and medication, where included.
- Emergency treatment: Eligible emergency medical care within the policy's coverage area.
- Cancer treatment: Oncology treatment subject to the policy's limits and conditions.
- Medical evacuation: Transportation to an appropriate medical facility when covered by the policy.
- Maternity, dental and optical care: Often optional benefits that can increase the premium.
What are the exclusions of international health insurance?
International health insurance commonly excludes pre-existing conditions and cosmetic procedures, along with non-medically necessary, experimental or out-of-area treatment.
- Pre-existing conditions: Coverage can vary based on medical underwriting, with some conditions excluded or subject to waiting periods.
- Non-medically necessary treatment: Insurers generally only reimburse treatment that meets the policy's medical-necessity requirements.
- Cosmetic procedures: Elective procedures performed primarily to change appearance are generally not covered.
- Experimental treatments: Treatments without sufficient clinical evidence or not accepted under the insurer's criteria may be excluded.
- Geographical exclusions: Treatment outside the policy's coverage area may leave the insured responsible for the full cost.
- Benefit limits: A covered treatment can still result in out-of-pocket costs when expenses exceed the policy's annual or specific benefit limits.
- Optional benefits: Dental, optical and maternity care may require additional coverage and therefore a higher premium.
How can expats reduce international health insurance costs?
Expats can reduce international health insurance costs by choosing a higher deductible, limiting geographical coverage and removing benefits they do not need.
- Choose a higher deductible: Taking on more upfront medical costs can lower the premium.
- Exclude US coverage: If US treatment is not needed, worldwide coverage excluding the US can be less expensive.
- Choose regional coverage: A regional policy may cost less than worldwide coverage if you only need protection in a specific area.
- Remove unnecessary benefits: Optional dental, optical, maternity or outpatient coverage can increase premiums.
- Compare policies based on coverage: Check deductibles, benefit limits, exclusions and geographical coverage alongside the premium.
Conclusion
The real cost of international health insurance is often determined after a claim occurs, not when the premium is paid.
A policy that appears inexpensive can offer limited value if its benefit caps, exclusions or reimbursement conditions leave substantial medical bills to the insured.
For expats, it is also worth considering how healthcare needs may evolve alongside their lifestyle.
A policy that works well while young and healthy may become less suitable after retirement, a relocation to a higher-cost healthcare market or a change in family circumstances.
Reviewing the policy before these changes occur can prevent cost from becoming the only consideration.
FAQs
What country has the highest cost of health insurance?
The United States had the highest average international private medical insurance cost in the 2025 SIP Health Cost Index, at approximately US$17,969 per year across its standardized profiles.
Which health insurance has the lowest rates?
SafetyWing currently has among the lowest published rates for international/nomad health cover, starting at US$62.72 per four weeks for ages 18–39, although it is a nomad-focused product rather than a like-for-like comprehensive international private medical insurance policy.
Is premium the same as coverage?
No. The premium is what you pay for an insurance policy, while coverage is the medical treatment and expenses the insurer agrees to pay under its terms.
A higher premium does not automatically mean broader coverage, so expats should compare the benefits, coverage limits, exclusions, deductibles and geographical area alongside the premium.
Will insurance premiums increase every year?
No, insurance premiums do not automatically increase every year, but they frequently increase at renewal.
Medical inflation, rising healthcare costs, changes in age and claims experience can all contribute to higher premiums.
Related Articles
- Health Insurance for Expats Over 70: Options, Age Limits and Costs
- Expat Health Insurance Over 80: What Options Are Available?
- International Health Insurance With Maternity Coverage: A Global Guide
- International Health Insurance for Remote Workers Guide
- Choosing the Best Health Insurance for Expat Families Overseas
- Best Countries for Affordable Healthcare for Expats
- What to Do When Your Cigna Global Premium Increases: Compare Coverage, Costs, & Alternatives